BFSI
Banking Stocks Q2 FY27: Why Higher NII May Not Mean Higher Profit
Explore the intricacies of banking stocks for Q2 FY27 in our latest Insight Carousel. While Net Interest Income (NII) growth is often seen as a positive sign, this analysis delves into why higher NII may not always translate to higher profits for banking sector India players. We examine the crucial factors influencing bank profitability, including Net Interest Margins (NIMs) and the impact of bank provisions. Understand how asset quality plays a role in the financial health of Indian banking stocks like Kotak Mahindra Bank, HDFC Bank, and SBI. This content offers a nuanced look at banking results Q2 FY27, moving beyond headline numbers to provide a deeper understanding of the performance of these key financial institutions.
Explore the intricacies of banking stocks for Q2 FY27 in our latest Insight Carousel. While Net Interest Income (NII) growth is often seen as a positive sign, this analysis delves into why higher NII may not always translate to higher profits for banking sector India players. We examine the crucial factors influencing bank profitability, including Net Interest Margins (NIMs) and the impact of bank provisions. Understand how asset quality plays a role in the financial health of Indian banking stocks like Kotak Mahindra Bank, HDFC Bank, and SBI. This content offers a nuanced look at banking results Q2 FY27, moving beyond headline numbers to provide a deeper understanding of the performance of these key financial institutions.
More in BFSI
BFSI
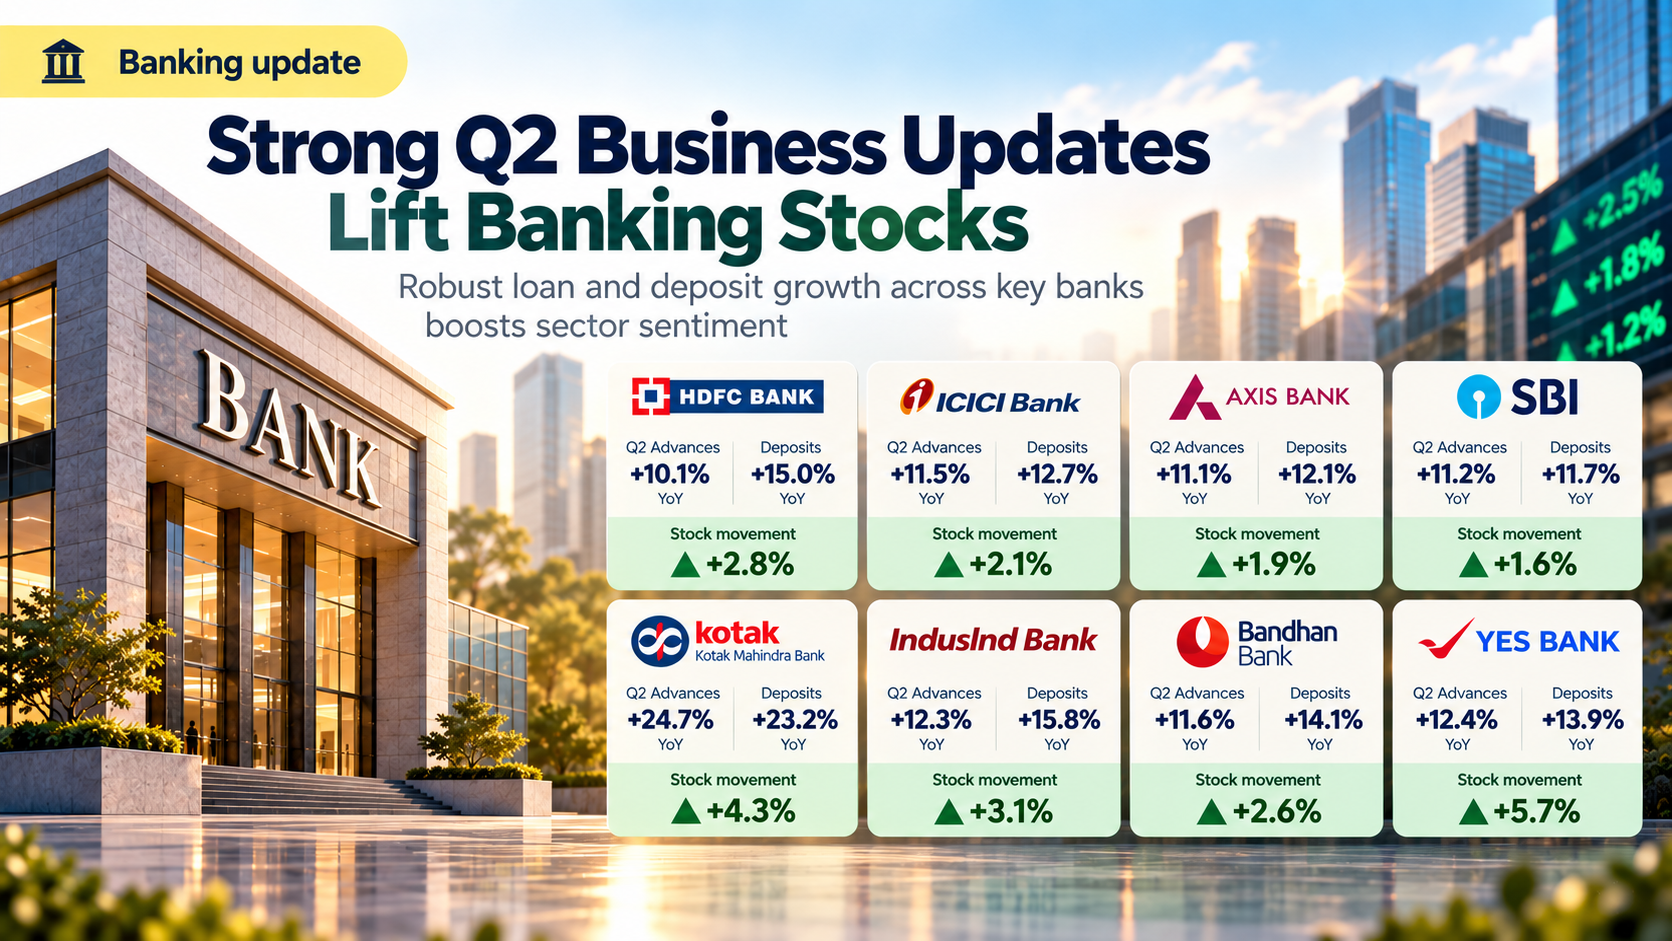
Kotak Mahindra Bank Shows Strong Q2 Growth as Loans and Deposits Rise Over
- Kotak’s loan growth stayed strong, showing that credit demand remained healthy in quarter
- Deposits grew as quickly as advances, giving Kotak a stronger base to fund future lending
- CASA deposits increased, although their 11.3% growth lagged the bank’s overall deposits
BFSI
YES Bank Sees Strong Q2 Growth as Loans Rise 24% and Deposits 20%
- YES Bank is lending much faster, but can its deposits keep pace with this growth?
- More loans can lift earnings, however the bank still needs enough low-cost deposits
- The falling CASA ratio raises a simple question: is deposit growth getting costlier?